Ethical Sustainability reporting for SECR and other disclosures is transparent and designed to be easily assure-able. We align as far as is possible from our position with the International Ethics Standards Board for Accountants (IESBA) standards for sustainability reporting, the International Ethics Standards Board for Accountants (IESBA). This means that when considering “renewable” electricity contracts, we want to be as careful as possible to ensure they are high quality.
The Science-Based Targets Initiative set standards for renewable generation which can be a challenge to meet via traditional supply contracting.
“Market instruments shall be limited to LCE generators commissioned or re-powered within fifteen years preceding the period of electricity consumption to which the instrument is applied.”
https://standards.sciencebasedtargets.org/
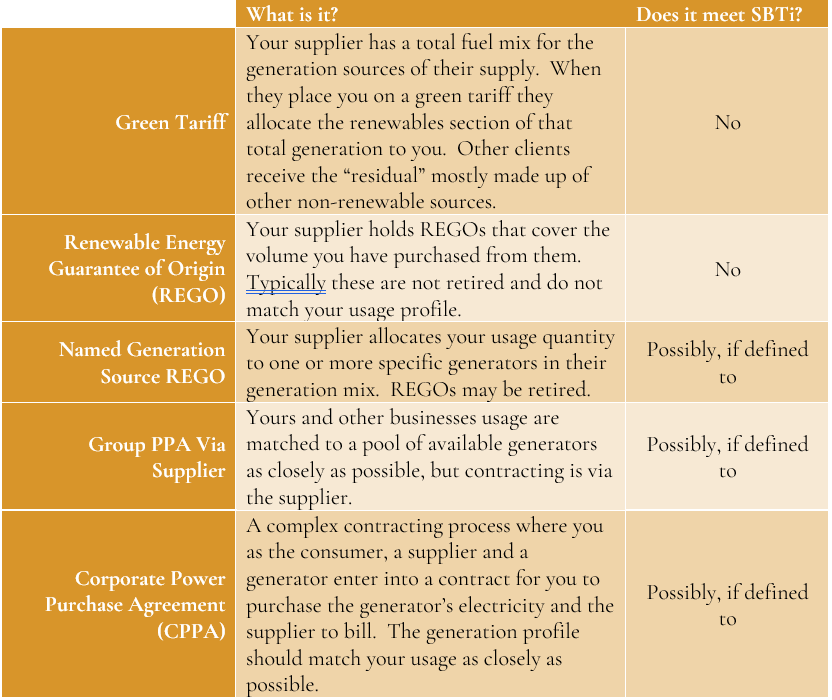
With those of the above that can meet the requirements for reporting under SBTi, you can see that the crucial thing is to ensure that your specific contract is defined in such a way to meet them – if you go into procurement without defining those needs there is a risk that you still miss them even with an expensive CPPA agreement.
Outside of choosing whether and how to reduce the carbon footprint of your Scope 2 emissions, there are other crucial considerations too, which we address in this article ‘C’.